pre-approval process
The Home Loan Pre-Approval Process in Australia: Step-by-Step Timeline, Documents and What Happens Next (2026)
The home loan pre-approval process has five steps: an initial conversation with a broker or lender, gathering documents, choosing a lender, a credit assessment, and an outcome letter. Speed depends mostly on how quickly you supply complete documents. Approval is conditional, typically lasts 3 to 6 months, and is not a guarantee of final finance.
You probably know what pre-approval is. What most buyers do not know is the order of events, where applications stall, and how to protect the approval once they start inspecting or bidding. A pre-approval that lapses or falls over mid-search costs you time, and sometimes a property you wanted.
This guide walks through the process as it actually runs, from first conversation to unconditional approval. You will get a document checklist, a list of what derails approvals, advice on expiry, and how to use your approval at auction and in a private sale.
Key Takeaways
- Pre-approval is an indicative assessment, not a loan. Formal approval only comes after you have a signed contract and the lender has valued the property.
- Document gathering is usually the slowest step because it depends on you, not the lender.
- Each credit application leaves an enquiry on your credit file, so apply through one considered pathway rather than shopping around yourself.
- New debt, a job change, buy now pay later (BNPL) accounts and unexplained transactions are the most common reasons an approval falls over.
- Most approvals are valid for around 3 to 6 months, so treat the expiry date as part of your search timeline.
- The pre-approved amount is the lender's ceiling, not your budget. Set your own lower, firm limit before you bid.
Summary Table: Pre-Approval, Conditional Approval and Unconditional Approval
The terms overlap, and lenders do not always use them the same way. This table shows the stages in the order you will meet them.
| Stage | What it means | Tied to a property? | What still needs to happen |
|---|---|---|---|
| Pre-approval | Indicative assessment of what the lender is likely to lend, based on your finances | No | Find a property, sign a contract, lodge a formal application |
| Conditional approval | Formal assessment for a specific purchase, subject to conditions | Yes | Valuation, contract and insurance checks, verification of your details, any extra documents |
| Unconditional approval | Every condition is satisfied and the lender will fund the loan | Yes | Sign loan documents, arrange settlement |
Pre-Approval vs Conditional vs Unconditional Approval: What Each One Means
Pre-approval is a lender's indicative view of what it would lend you, before you choose a property. Conditional approval is a formal decision tied to a specific property, subject to conditions. Unconditional approval means every condition is met and the lender will fund settlement. Each stage removes risk, and only the last one is certain.
The naming is where buyers get confused. Some lenders call a pre-approval a "conditional approval". Others reserve that phrase for the stage after you have a contract. Ask your broker or lender what exactly their letter means and what it assumes. According to ASIC's Moneysmart (https://moneysmart.gov.au/home-loans), pre-approval is not a guarantee that you will get the loan.
The conditions attached to a pre-approval are not boilerplate. They usually include:
- A satisfactory valuation of the property you choose
- The property type being acceptable to the lender
- Your income, employment and debts being the same as when you applied
- Verification of your documents and identity
- Satisfactory review of the contract of sale
The key point is timing. Pre-approval happens before you shop. Conditional approval happens after you have a contract. Unconditional approval happens shortly before settlement. If you only plan around the first stage, you will be surprised by the other two.
The Home Loan Pre-Approval Steps, From First Call to Outcome
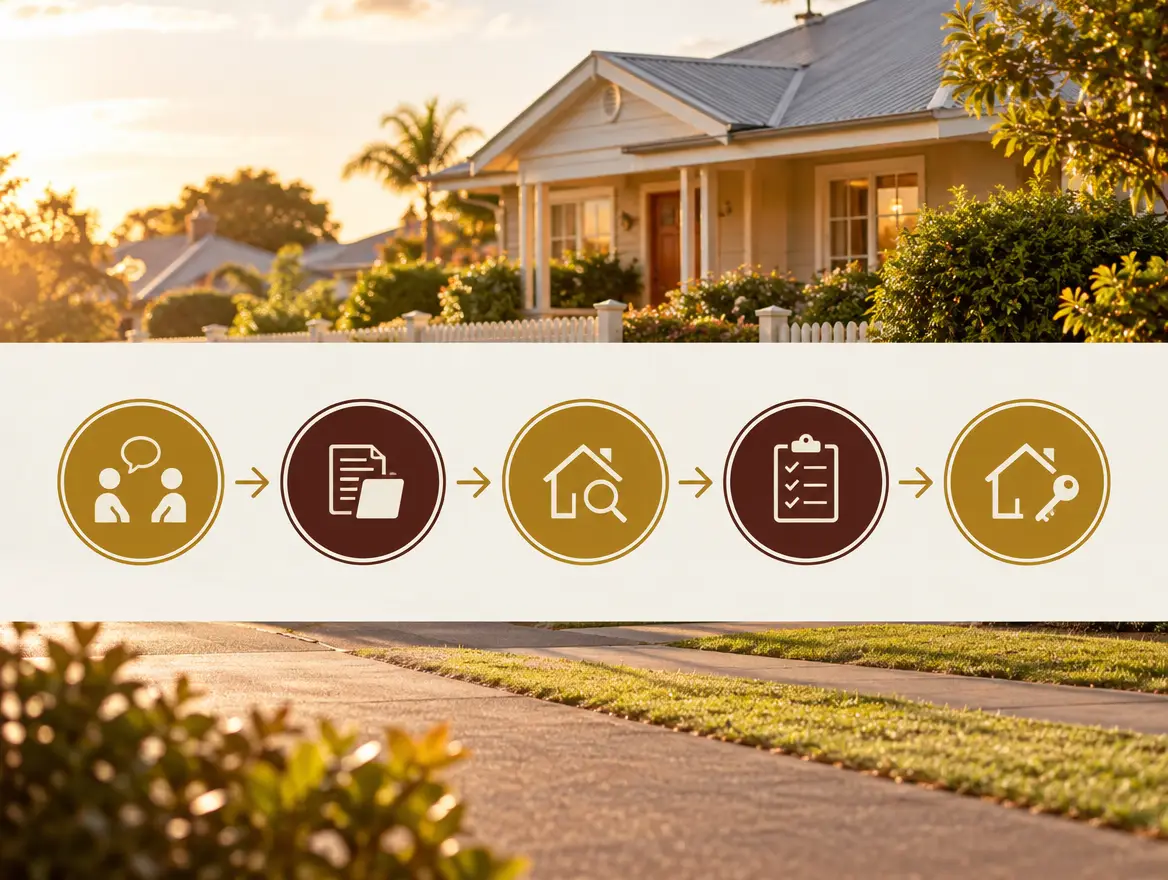
There are five steps: an initial conversation, document gathering, lender selection, credit assessment and the outcome. The slowest step is usually document gathering, because it depends on you rather than the lender. Lender turnaround varies with volume and policy, so ask your broker for current timeframes instead of relying on a generic number.
I have deliberately not put a day count on each step. Lender processing times move week to week, and any fixed number you read online is a guess. What you can control is how fast you move through the steps you own.
| Step | Who drives it | What affects speed |
|---|---|---|
| 1. Initial conversation | You and your broker | How clear your goals and numbers are |
| 2. Document gathering | You | Whether your documents are complete and current |
| 3. Lender selection | Your broker | How well your profile fits lender policy |
| 4. Credit assessment | The lender | Lender workload and any follow-up questions |
| 5. Outcome | The lender | Whether conditions and expiry are clearly stated |
Step 1: The initial conversation
This is a fact-finding session. Expect questions about your income, employment type, savings, existing debts, dependants, and the type of property and suburb you are targeting. Your broker also needs to know whether you want to avoid Lenders Mortgage Insurance (LMI). According to ASIC's Moneysmart (https://moneysmart.gov.au/home-loans/lenders-mortgage-insurance), LMI generally applies when you borrow more than 80% of the property's value, so your deposit size shapes the whole plan.
First home buyers should also ask which government support might apply. Housing Australia (https://www.housingaustralia.gov.au) runs the Home Guarantee Scheme, which can let eligible buyers purchase with a smaller deposit without paying LMI. Eligibility rules change, so confirm them before you rely on them.
Step 2: Document gathering
This is where most delays start. Missing payslips, bank statements that do not match what you declared, or a self-employed income file that is not up to date can stall the whole application. The full checklist is in the next section. Send everything in one organised pack and explain anything unusual up front.
Step 3: Lender selection
Lenders do not assess everyone the same way. They treat bonuses, overtime, casual income, rental income, HELP debts and BNPL accounts differently. Some are more cautious on certain property types. A broker matches your profile to a lender whose policy suits it, which is a big reason to avoid walking into a branch and applying cold.
This step also protects your credit file. Every application you lodge with a lender triggers a credit enquiry. Choosing the right lender once is better than applying to three and hoping.
Step 4: Credit assessment
The lender pulls your credit report, verifies your income, and assesses your living expenses and commitments. It then tests whether you could still afford repayments at a higher interest rate than the one you will actually pay. This buffer is why your approved amount can be lower than what a simple online calculator suggests. We cover that logic separately in our borrowing capacity content.
The lender may come back with questions: an unexplained deposit, a gap in employment, a credit card you forgot to mention. Answer quickly and completely. A slow reply here is the second most common cause of delay.
Step 5: The outcome
You will receive an approval letter, or a decline or a reduced amount. Read the letter, not just the headline figure. Check:
- The approved amount and the assumptions behind it
- The expiry date
- The conditions that must be satisfied
- Whether the interest rate is locked (it usually is not)
If the amount comes back lower than expected, ask exactly why. It could be a credit card limit you can close, or a debt you can pay down, and fixing it before you search is far cheaper than discovering it at contract stage.
Documents Needed for Pre-Approval: The Checklist
You will generally need proof of identity, proof of income, bank statements, a full list of your debts, evidence of genuine savings, and, if relevant, gift letters. Self-employed applicants need business and tax records as well. Requirements vary by lender, so treat this as the standard pack and confirm specifics with your broker.
Identification
- Driver licence or passport
- Medicare card or another secondary ID
Income (employed applicants)
- Recent payslips
- Employment contract or a letter from your employer, if you are new in the role
- Your most recent PAYG payment summary or income statement
Income (self-employed applicants)
- Personal and business tax returns
- ATO notices of assessment
- Recent BAS statements
- A letter or financials from your accountant
Lenders commonly want to see more than one year of self-employed income, and they usually assess it conservatively. If your latest year dipped, tell your broker early. Some lenders handle that better than others.
Bank statements and savings history
- Statements for your everyday, savings and offset accounts
- Evidence your deposit has been built up over time
Lenders look for genuine savings, meaning money you accumulated through regular saving rather than a sudden lump sum. A large unexplained deposit invites questions.
Debts and commitments
- Credit card statements showing limits (not just balances)
- Personal loans, car loans and any BNPL accounts
- HELP or other study debts
- Existing home loan statements, if you own property
Gifts and family support
- A signed gift letter from the person giving you money, confirming it does not need to be repaid
- Evidence of the funds arriving in your account
For upgraders and investors
- Current loan statements and a recent rates notice for each property
- Rental income evidence such as a lease or property manager statements
- An estimate of the current value of the property you may sell or borrow against
One practical tip: name your files clearly and send one complete pack. Half-sent documents create back-and-forth that adds days for no reason.
What Can Derail a Pre-Approval
The most common causes are multiple credit applications, new debts, job changes, BNPL accounts, high credit card limits and unexplained transactions. A lender's decision rests on your finances at the time they assess you and again before settlement. Anything that changes your risk profile in between can reduce or cancel the approval.
Multiple hard credit enquiries
When you apply for credit, the lender checks your credit file and the enquiry is recorded. ASIC's Moneysmart (https://moneysmart.gov.au/managing-debt/credit-reports-and-scores) explains that credit reports list the credit applications you have made, and other lenders can see them. A cluster of enquiries over a short period can suggest financial stress. Avoid applying for store cards, phone plans on credit, or several lenders' pre-approvals on your own.
New debts
A new car loan, personal loan or finance on furniture adds a repayment the lender must count. It also reduces what you can borrow. Consider this hypothetical:
A buyer receives a pre-approval and starts inspecting. Six weeks in, their car dies. They finance a replacement, which seems reasonable and is only a modest repayment. When they find a home and submit the formal application, the lender reassesses their commitments. The new loan lowers their borrowing capacity below the property's price, and the original approval no longer holds. Their search restarts, and the home sells to someone else.
The lesson is simple. Any new credit, even sensible credit, should go through your broker before you sign.
Job changes
Lenders want stable income. Changing employers, moving from permanent to casual or contract work, or starting a new business can all reset the assessment. A move within the same industry and at the same or higher pay is often manageable, but it still needs to be disclosed. Probation periods in a new role are a particular sticking point. Call your broker before you resign, not after.
Buy now pay later and credit card limits
Lenders look at BNPL accounts in your bank statements and, increasingly, on your credit file. Even a clear balance can signal reliance on short-term credit. Credit cards are assessed on their limit, not the balance, so an unused card with a high limit still reduces your borrowing capacity. Closing cards you do not need, or reducing limits, is often one of the easiest ways to improve an approval before you apply.
Unexplained transactions
Lenders review your statements line by line. Regular gambling, large cash withdrawals, frequent overdrafts and unexplained transfers all draw attention. You do not need a perfect statement, but you do need to be ready to explain what is on it. Clean up your spending habits in the months before applying if you can.
Pre-Approval Expiry and Staying Approval Ready
Most pre-approvals are valid for around 3 to 6 months, though the exact period depends on the lender. After that, the lender needs to reassess you. Interest rates and lending policy can also change during that period, so the amount you were approved for is a snapshot, not a promise.
Put the expiry date in your calendar the day you receive the letter, and set a reminder a few weeks before it. If you are still searching when the approval is close to lapsing, contact your broker early. Renewal usually means updated payslips and bank statements, and the lender may run a fresh credit check, which means another enquiry.
A renewal is also a reassessment. If your circumstances or the lender's policy have changed, the new amount can be higher or lower. That is why waiting until the week before a contract is signed to find out is a risky strategy.
What to avoid while you house hunt:
- Taking on any new debt, including car finance and BNPL
- Increasing credit card limits or opening new cards
- Changing jobs without speaking to your broker first
- Making large, unexplained transfers or withdrawals
- Applying for finance with another lender independently
- Letting your deposit savings dip, as lenders may recheck balances
What helps:
- Keep your savings pattern steady and visible
- Pay every bill and repayment on time
- Keep a copy of every document you submitted so the formal application is quick
- Tell your broker about any change in your life, even if it seems small
Using Pre-Approval at Auction and Private Sale
At auction, pre-approval tells you what a lender might lend, but your contract is unconditional, so you must set a firm ceiling below your maximum. In a private sale, you can usually add a finance condition, but the lender's valuation still decides how much you can actually borrow against the property.
At auction
Auction contracts are generally unconditional. There is no finance clause, and cooling-off rights generally do not apply to purchases at auction. If the hammer falls on your bid and your finance does not come through, you are still bound to settle. That risk is yours.
Before auction day:
- Set a ceiling below your pre-approved amount. Leave room for stamp duty, legal costs, moving costs and a buffer for rate rises.
- Check the contract and building and pest reports before the day, not after.
- Ask your broker how the lender is likely to value the property. If the valuation comes in under the price, you must cover the gap in cash.
- Decide your limit in advance and write it down. Auctions are built to make you drift past it.
At private sale
Private sale and offer-based sales usually let you negotiate conditions. A finance clause gives you time to secure formal approval, and a building and pest clause protects you from nasty surprises. A pre-approval letter also shows the seller you are serious, which strengthens your offer. Do not treat the finance clause as a safety net you can use freely, however. Sellers accept offers with fewer conditions more readily, and an approved buyer with a short finance period is often preferred.
Why lender valuation still matters
The lender lends against its own valuation, not your purchase price. If the valuation comes in below what you agreed to pay, the amount available shrinks, and your loan-to-value ratio (LVR) rises. Crossing the 80% LVR threshold can trigger LMI, which adds a cost on top of the purchase. Ask your broker about the lender's valuation approach early, especially in a fast-moving market where prices can run ahead of valuations.
What Happens After Pre-Approval: From Offer to Unconditional Approval
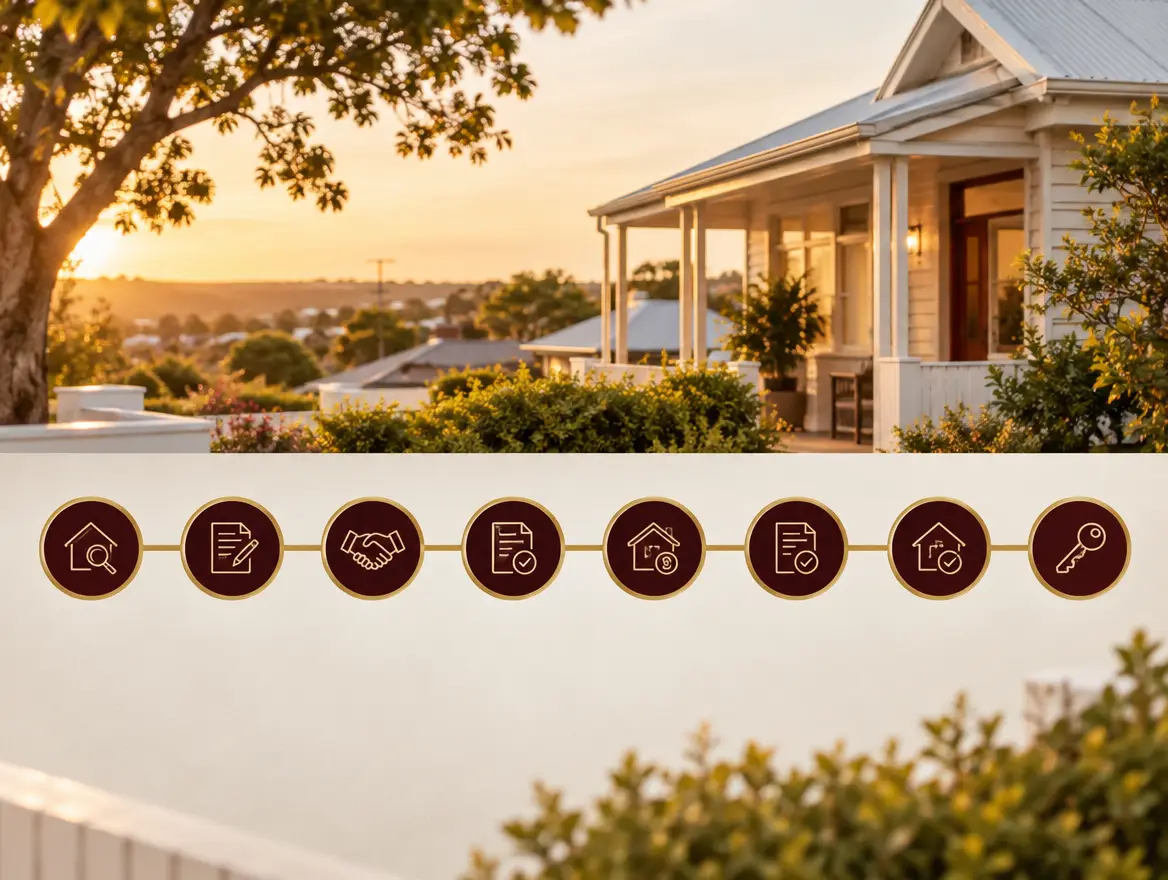
After pre-approval, you find a property, sign a contract, lodge a formal application, the lender values the property, and conditional approval is issued. You then satisfy the remaining conditions and receive unconditional approval before settlement. Each stage has its own checks, so keep your broker, conveyancer and advocate informed throughout.
The typical order looks like this:
- Search and inspect. Shortlist properties that fit both your needs and your lender's policy. Some lenders are cautious on certain property types, such as very small apartments or unusual titles, so check before you commit.
- Contract review. A conveyancer or solicitor reviews the contract before you sign. Do this before an offer, not after.
- Offer and contract. You make an offer or bid, and a contract is signed with any agreed conditions.
- Formal application. Your broker lodges the application with the signed contract and updated documents.
- Valuation. The lender arranges its own valuation of the property.
- Conditional approval. The lender issues approval subject to any remaining conditions, such as insurance or verification of your details.
- Satisfy conditions. Provide whatever is outstanding.
- Unconditional approval. The lender confirms it will fund the loan.
- Loan documents and settlement. You sign loan documents, arrange building insurance, do a pre-settlement inspection, and settle.
Investors follow the same path, but the lender also assesses rental income and your existing property position. If you are lining up your next purchase, make sure your broker has current loan statements and rental evidence ready. We cover loan structure for investors in our investment property loans content.
Why We Treat Pre-Approval as a Starting Line, Not a Budget
My position is simple: the amount on your pre-approval letter is the lender's maximum, not your budget. Buyers who bid to the top of it have no room for rate rises, repairs or a valuation shortfall. The best buyers I see set their own, lower limit before they start.
There is also a coordination problem that most guides ignore. Finance, property search and the purchase itself are usually handled by three separate parties who rarely talk to each other. The broker does not know which properties you are inspecting. The agent does not know your ceiling. Nobody checks whether a property suits your lender until it is too late.
Preparation is what wins deals. In January 2021 I sold the first apartment in a Beenleigh complex for a developer who was openly sceptical that I could add much. Five years on, we have sold 12 apartments in that complex. I was up against exceptional agents, and what made the difference was knowing everything about the complex and the body corporate, walking buyers through it, and taking a genuine interest in what each purchaser needed. That same preparation applies to finance. A buyer who understands the property, its running costs and how the lender will value it goes into contract stage with far fewer surprises.
This is why George & Sons runs pre-approval, property search, buyers advocacy and settlement as one coordinated process. The finance team knows what you are looking for, and the search team knows your ceiling. When something changes, one conversation fixes it instead of three.
Ready to get your finance in order? Book a pre-approval consultation with the George & Sons finance team. If you want a coordinated purchase from approval to settlement, ask us about pairing pre-approval with our buyers advocacy service.
References
- ASIC Moneysmart, Home loans
- ASIC Moneysmart, Lenders mortgage insurance
- ASIC Moneysmart, Credit reports and scores
- Housing Australia, Home Guarantee Scheme information
Get tailored guidance
Send us your question and we will reply within one business day.
Send us the article topic, suburb, or property goal you want help with and we will reply within one business day.
Send my questionFAQ
How long does pre-approval take?
There is no fixed number, because it depends on how quickly you supply complete documents and on the lender's current workload. Document gathering is usually the slowest step. Ask your broker for the lender's current turnaround, and have your full document pack ready before you apply.
How long does a pre-approval last?
Most pre-approvals are valid for around 3 to 6 months, depending on the lender. Check the expiry date on your approval letter. If you are still searching close to that date, ask your broker about renewal early, as it usually requires updated documents and may involve a fresh credit check.
Can a lender refuse my loan after pre-approval?
Yes. Pre-approval is not a guarantee. The lender can decline or reduce the loan if the property valuation is low, the property type does not meet its policy, or your finances, employment or credit file change between pre-approval and formal application.
Does applying for pre-approval affect my credit file?
Yes. When you apply for credit, the lender checks your credit report and the enquiry is recorded on your file, where other lenders can see it. Applying to several lenders yourself creates several enquiries, so it is usually better to go through one broker who selects the right lender first.
What is the difference between conditional and unconditional approval?
Conditional approval means the lender has agreed to lend for a specific property, subject to conditions such as a satisfactory valuation and verification of your details. Unconditional approval means all those conditions have been met and the lender will fund the loan at settlement.
Margy George
Property and finance guidance from the George & Sons team.
Keep reading
borrowing capacity
Borrowing Capacity in Australia: How Lenders Calculate It and 7 Ways to Increase It in 2026
21 min read
how to buy a house at auction
How to Buy a House at Auction in Australia: A Buyer's Complete Guide for 2026
22 min read
first home buyer finance
First Home Buyer Finance in Australia: Grants, Schemes, Deposits and How to Fund Your First Purchase in 2026
16 min read
Ipswich 4300
Selling or renting out in 4300?
We specialise in sales and property management across the 4300 postcode. Pick your suburb for local rents, Census figures and how we work there.
Selling
Ready for clarity?
Get a calm, practical plan for your next property move.
Buying, selling, finance, or renting - tell us what you are working on and we will come back with the most useful next step.
Tell us what you need help with.
Send a quick enquiry and the team will come back with a clear next step.
Request a callback