borrowing capacity
Borrowing Capacity in Australia: How Lenders Calculate It and 7 Ways to Increase It in 2026
Borrowing capacity is the maximum a lender will assess you can repay on a home loan. Australian lenders calculate it by taking your verified income, subtracting the higher of your declared living expenses or the HEM benchmark and existing debts, then testing repayments at the interest rate plus APRA's 3 percentage point serviceability buffer.
Most buyers meet their borrowing capacity for the first time as a number on a screen. It is often lower than expected, and nobody explains why. The reason is simple: capacity is the output of a credit policy, not a measure of your wealth or your discipline.
This guide shows how Australian lenders build that number, why two lenders can return very different answers, and which seven changes lift it. It also covers investors, and how to turn your figure into a firm budget before you inspect a single property. This is general information, not personal financial advice.
Key Takeaways
- Borrowing capacity, pre-approval and comfortable repayments are three different numbers. Only one of them is a lender decision.
- Lenders test your loan at a rate well above the actual rate, using APRA's minimum serviceability buffer of 3 percentage points.
- Your declared expenses are compared with the HEM benchmark, and the higher figure is generally used.
- Unused credit card limits count against you. Reducing or closing them is often the fastest way to lift capacity.
- Lenders use different policies for income shading, expenses and debts, so the same buyer can get very different answers.
- Set your purchase budget below your maximum, then search within it.
Summary Table: What Drives Your Borrowing Capacity
| Factor | How lenders typically treat it | What you can influence |
|---|---|---|
| Base salary | Counted in full once verified | Low, but accurate documentation helps |
| Bonuses, overtime, commission | Usually shaded or averaged over a history | Medium: build and document a track record |
| Rental income | Shaded to allow for vacancy and costs | Medium: lease evidence and appraisals |
| Living expenses | Higher of declared spending or HEM | High: accurate, trimmed spending |
| Credit card limits | Assessed on the limit, not the balance | High: reduce or close unused limits |
| Personal, car and BNPL debts | Repayments counted as commitments | High: clear or consolidate |
| Loan term | Longer terms lower assessed repayments | Medium: trade-off with total interest |
| Co-borrower | Adds income, also adds their debts and expenses | High: depends on their position |
| Lender choice | Policy varies widely | High: compare across lenders |
What Is Borrowing Capacity and How Is It Different From Pre-Approval?
Borrowing capacity is the largest loan a lender calculates you could service under its credit policy. It is not a pre-approval, which is a conditional lender decision, and it is not what you can comfortably repay, which is a personal judgement about your lifestyle and risk tolerance.
These three numbers are routinely confused, and the confusion costs buyers money.
Borrowing capacity is an estimate. A broker, bank or online calculator runs your income, expenses and debts through a lender's rules. It tells you what is theoretically possible.
Pre-approval (also called conditional approval) is a lender's formal view, subject to conditions. These usually include a satisfactory property valuation, unchanged circumstances and verification of your documents. Pre-approvals expire, and your circumstances can change before they do.
Comfortable repayments are the figure that matters for your sleep. Lenders test your loan at a higher rate than you will actually pay, so the maximum capacity figure can still leave you with a tight household budget. School fees, childcare, travel and aspirations for the next five years are rarely captured in a bank's model.
Your capacity also does not equal your purchase price. The price you can pay is your loan plus your deposit, minus costs such as stamp duty, legal fees and lender charges. Stamp duty varies by state and territory, so the same capacity buys a different price in Queensland than in Victoria.
How Do Australian Lenders Calculate Borrowing Capacity?
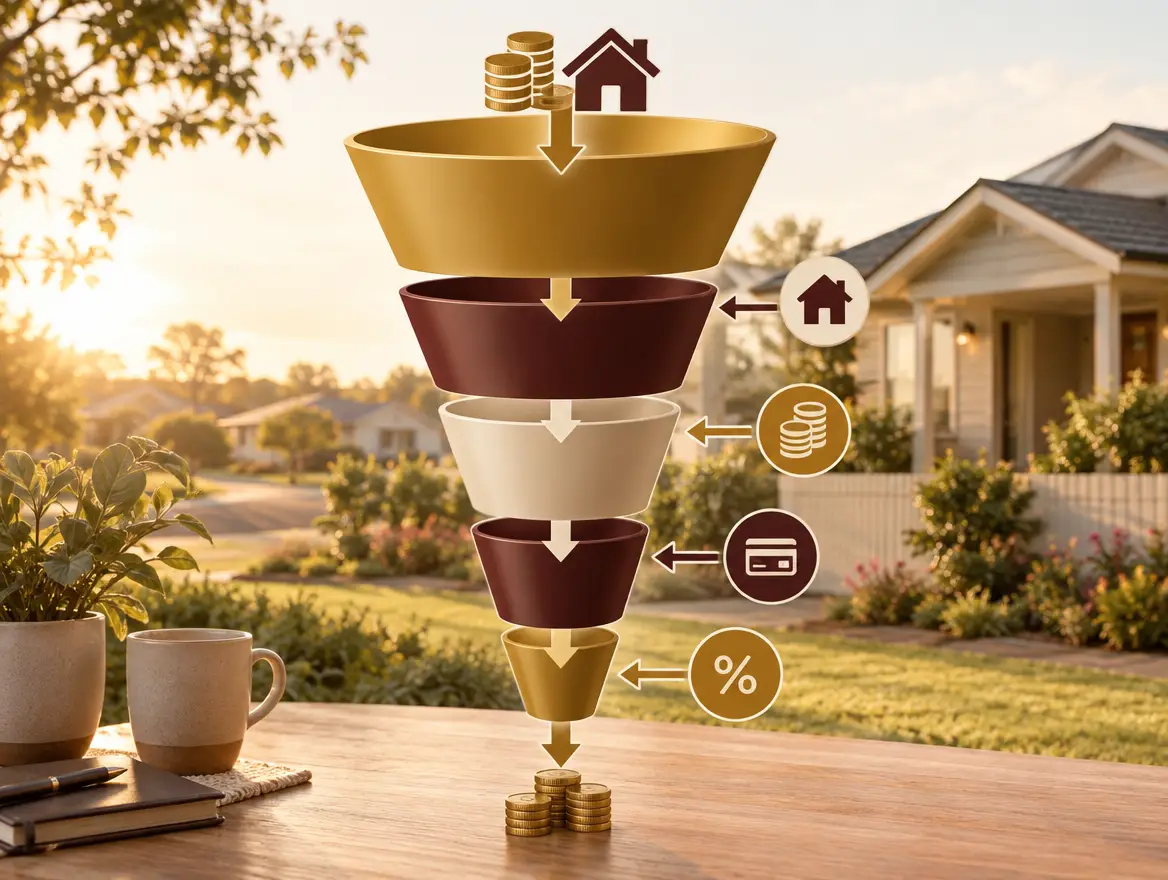 Lenders calculate borrowing capacity by working out your net income, deducting your living expenses and existing debt commitments, and then checking how large a loan you could repay at a stress-tested interest rate. Each step involves a policy choice, which is why outcomes differ.
The process looks like a funnel. Income goes in at the top. Living costs, debt repayments and a rate buffer are subtracted. What remains is the monthly repayment you can support, which converts to a maximum loan size.
Income shading: not every dollar counts equally
Lenders accept base salary readily once they have payslips and bank statements. Other income is treated with more caution. Bonuses, overtime, commissions and allowances are often averaged over a period or shaded, meaning only part of the amount is counted.
Rental income is also shaded. The lender assumes vacancy periods, agent fees, maintenance and other holding costs, so a portion of the rent is excluded from your assessed income. Casual and contract income is usually accepted after a history of continuous work. Self-employed borrowers are typically assessed on tax returns and notices of assessment, which often show lower income than the business generates because of legitimate deductions.
The practical point: two buyers on the same headline income can have different assessed incomes depending on how it is earned and documented.
Living expenses and the Household Expenditure Measure (HEM)
Lenders must make reasonable inquiries about your expenses under Australia's responsible lending rules, which ASIC administers. Most use the Household Expenditure Measure (HEM), a benchmark published by the Melbourne Institute that estimates typical spending based on household income, location and family composition.
The common approach is to compare your declared expenses with the HEM figure and use whichever is higher. That means understating your spending does not help. If you declare less than the benchmark, the benchmark is used anyway. If you declare more, your higher number is used, and your capacity falls.
Some lenders add their own expense models on top of HEM. Others scrutinise bank statements line by line for discretionary spending such as dining, subscriptions, gambling and travel.
The APRA serviceability buffer
APRA, the prudential regulator, requires banks and other authorised deposit-taking institutions to assess loan serviceability at a rate above the actual product rate. In October 2021 APRA lifted this buffer from 2.5 to 3 percentage points, and 3 percentage points is the current minimum at the time of writing. Check APRA's website for any later change.
Here is how it works. Imagine a loan carrying a hypothetical rate of 6 per cent. The lender tests whether you can afford repayments at 9 per cent. That is a purely illustrative figure, not a lender quote, but it shows why the repayment you are assessed on is far higher than the repayment you will make.
The buffer is a minimum. Lenders can apply a higher buffer or a minimum assessment rate (a floor), and some do. This is one of the main reasons lenders return different numbers.
Existing debts and credit card limits
Existing debts reduce capacity because their repayments come out of your assessed surplus. Car loans, personal loans, HELP debt repayments, buy now pay later (BNPL) accounts and other mortgages all count.
Credit cards are treated differently from other debts, and this surprises people. Lenders assess the limit, not the balance. A card with nothing owing still reduces capacity, because the lender assumes you could use all of it. Many lenders assess a fixed percentage of the limit as a monthly repayment, and that percentage is set by each lender's policy.
Worked example: a $10,000 credit card limit
This example uses assumptions that I am stating openly, because lender policies differ. It is illustrative, not a lender quote.
- Assume the lender treats 3 per cent of a card limit as a monthly commitment. A $10,000 limit becomes a $300 monthly commitment, even with a zero balance.
- Assume a hypothetical assessment rate of 9 per cent per year over a 30-year term. At that rate, each $100,000 borrowed costs about $805 a month in assessed repayments.
- Your $300 commitment removes $300 from the monthly repayment you can support. Dividing $300 by $805 and multiplying by $100,000 gives roughly $37,000.
So in this simplified example, a single $10,000 card you never use could lower your borrowing capacity by around $37,000. Two such cards would roughly double the effect. The real figure depends on tax, your HEM result and your lender's method, but the direction and rough scale hold up. This is why we ask about every card limit in the first conversation.
What Is the Debt-to-Income Ratio in Australia and What Are APRA's Current Settings?
A debt-to-income (DTI) ratio is your total debt divided by your gross annual income. A household earning $150,000 with $900,000 of total debt has a DTI of six. In Australia, APRA now limits how much new lending banks can write at DTI ratios of six or higher.
DTI is a blunt measure compared with a full serviceability assessment. It ignores your expenses and the interest rate. Regulators like it because it captures how stretched borrowers are relative to income, regardless of interest rate conditions.
Total debt for DTI purposes typically includes the new home loan, existing mortgages, personal loans, car loans, credit card limits and sometimes HELP debt. Lenders treat each item somewhat differently, so check the specifics.
APRA announced in September 2025 that from 1 February 2026 it would cap each authorised deposit-taking institution's new lending at a DTI of six or more at 20 per cent of new lending, with owner-occupier and investor lending measured separately. Confirm the exact settings on APRA's website, because the regulator adjusts these tools over time.
Here is what that means in plain language:
- It is a limit on a lender's share of lending, not a rule that declines every borrower above six times income.
- You will not automatically be refused at a DTI of six. But expect lenders to be more selective with high-DTI applications, particularly where deposits are small.
- Lenders can set stricter DTI limits of their own. Some already do.
- Investors with existing loans and multiple properties are more likely to approach high DTI, because debt accumulates faster than income.
DTI is a second filter on top of serviceability. You can pass the serviceability test and still hit a lender's DTI ceiling, which is another reason to model your position across several lenders rather than one.
Why Do Borrowing Capacity Results Vary Between Lenders and Calculators?
Results vary because every lender applies its own policy to income shading, expenses, debts, assessment rates and loan structure. APRA sets the minimum buffer, but lenders choose everything else. Online calculators add further variation because they use generic assumptions and cannot see your credit file or documents.
The main sources of difference are:
- Income treatment. One lender counts overtime after six months of history, another wants two years. Rental income shading varies. Some lenders accept government payments such as Family Tax Benefit, others limit them.
- Expense modelling. Some lenders rely on HEM. Others apply their own models or scrutinise statements harder.
- Assessment rate. The buffer is a minimum, and floor rates differ.
- Credit card and debt treatment. The percentage assessed on card limits differs, as does the treatment of BNPL and HELP debt.
- Interest-only and structure. Most lenders assess interest-only loans on principal and interest repayments over the remaining term, which cuts capacity compared with a simple interest-only calculation.
- Self-employed and variable income. Policies differ sharply on how many years of tax returns are needed and which income is accepted.
Online borrowing capacity calculators, including ASIC's MoneySmart tool, are useful for a first-pass figure. They are not lender decisions. A calculator typically assumes a fixed buffer and a standard expense profile. It does not know that you have two cards, an upcoming bonus history or a partner with HELP debt.
Treat a calculator as a rough guide to the order of magnitude. Treat a lender-specific assessment as the real information. A mortgage broker or finance team that models multiple lenders side by side will show you the spread, and that spread can be large enough to change which properties you can consider.
How Can You Increase Your Borrowing Capacity? 7 Practical Ways
You can increase borrowing capacity by lowering your assessed commitments, documenting all of your income, reviewing your expenses accurately and choosing a lender whose policy suits your profile. The seven steps below are listed roughly in order of how quickly they can move the number.
1. Reduce or close credit card limits
This is usually the quickest fix. As the worked example shows, a $10,000 limit can lower capacity by tens of thousands of dollars even if you never use it. Ask your card provider to reduce the limit to what you genuinely need, or close the card entirely.
Make sure closure is actually processed. Cutting up a card does not remove the limit. Get written confirmation, and allow time for your credit file to reflect the change before applying.
2. Clear personal loans, car loans and BNPL accounts
Every loan repayment is subtracted from your assessed surplus. A short-term personal loan or car loan with a modest balance can cost you more capacity than its size suggests, because the repayment is counted in full each month.
BNPL accounts deserve attention too. Even if they feel small, lenders see the pattern in your statements and may count the commitments. Clearing them and ceasing use well before applying is sensible.
Consider this illustrative scenario, not a real client result. A buyer has two credit cards and a personal loan, all of which the lender assesses as monthly commitments. The buyer also has savings sitting in a low-interest account. Using part of those savings to clear the personal loan and closing one card removes three commitments from the assessment. The deposit is a little smaller, but the assessed surplus is larger. Whether that trade works depends on the numbers, which is why we model the options before a client acts, not after.
3. Review your declared expenses accurately
Be honest and be precise. Lenders compare your declared spending with HEM and with your bank statements. Understating expenses can lead to a decline, and under responsible lending obligations it is a risk for you as well as the lender.
What you can do is genuinely reduce discretionary spending in the months before applying. Cancel unused subscriptions, reduce dining and entertainment, and stop gambling transactions. Statements covering a few clean months present a stronger picture than a rushed budget on an application form.
4. Consider loan term and structure
A 30-year term produces lower assessed repayments than a 25-year term, which increases capacity. The trade-off is more total interest over the life of the loan. Many borrowers take the longer term for assessment and make extra repayments later.
Structure matters too. Interest-only periods rarely help with capacity because lenders typically assess them over the shorter remaining principal and interest term. Splitting a loan or using an offset account can suit your cash flow, but check how each lender treats the structure in its assessment.
5. Add a co-borrower
A partner's income can lift capacity significantly. But a co-borrower brings their own debts, credit card limits, HELP repayments and expenses, plus any dependants. Sometimes adding a second borrower helps less than expected, and occasionally it hurts.
For some buyers, a family guarantee from parents is another route, which can reduce the deposit needed. It carries real obligations for the guarantors, so get independent advice first.
6. Document all your income
Income that is not documented is income that is not counted. Gather payslips, tax returns, notices of assessment, employer letters and evidence of regular bonuses, overtime, commission, rental income and side income. For the self-employed, keep tax returns and BAS lodgements current.
Lenders also look at consistency. A bonus paid for three consecutive years is far easier to count than one received once. If you expect a pay rise or a new contract, ask whether the lender will accept it now or only after probation or a track record.
7. Choose the right lender
Because policy differs so widely, lender choice can move your capacity more than any single financial change. A lender that accepts your income type generously and treats your debts favourably may offer a materially higher number than one that does not.
This is where modelling across lenders earns its keep. Our finance team compares how multiple lenders would treat your specific profile, so you see the range before you commit. Avoid submitting full applications to several lenders in quick succession, because each credit enquiry is recorded on your file.
How Is Borrowing Capacity Assessed for Investors?
For investors, lenders count part of the expected rental income, deduct the costs of holding the property, and test all loans at the buffered assessment rate. Negative gearing losses are treated differently by each lender, and existing investment debts reduce capacity for the next purchase.
Rental income is typically shaded to allow for vacancy, agent fees, rates, insurance and maintenance. Only a portion of the rent is added to your assessed income. The lender will usually want a lease or a rental appraisal from an agent.
Negative gearing is where an investment property's costs exceed its rent, and the loss can be offset against other taxable income, according to the Australian Taxation Office's rules for rental properties. The tax benefit is real, but lenders do not all give credit for it when assessing serviceability. Some use a pre-tax approach, others consider tax effects, and policies differ again for negatively geared properties versus positively geared ones.
Other investor-specific points:
- Existing investment loans. They are assessed at the buffered rate, usually on a principal and interest basis, even if you pay interest-only. This can erode capacity quickly as your portfolio grows.
- DTI. Investors accumulate debt faster than income, so a lender's DTI ceiling can become the binding constraint before serviceability does. APRA's DTI limit applies to investor lending separately.
- Equity. Using equity in an existing property for a deposit increases debt, and the new debt counts in full.
If you are planning more than one purchase, sequence matters. Buying in a different order, or restructuring existing loans first, can change what is available later. Our guides on investment property loans and refinancing cover the structural options in more depth.
How Do You Turn Your Borrowing Capacity Into a Buying Strategy?
Turn your capacity into a strategy by setting a budget below your maximum, factoring in purchase costs and ongoing expenses, then searching only within that range. Confirm your numbers before you inspect, because falling for a property priced above your real budget is the most expensive mistake buyers make.
Here is a practical sequence:
- Get a lender-modelled capacity figure first. Do this before attending any open home, not after you have found a favourite.
- Subtract purchase costs. Stamp duty, legal and conveyancing fees, inspections, lender fees and moving costs reduce what you can spend on the price.
- Set a comfortable repayment, not a maximum one. Work out what repayments you could sustain if rates rose and one income fell. Your budget is the lower of that figure and your capacity.
- Account for ongoing costs. Council rates, insurance, maintenance and, for apartments and townhouses, body corporate levies.
- Search within your range. Browse listings that sit at or below your confirmed price point, and keep a small gap between your ceiling and your target.
- Bring in a buyers advocate when the stakes justify it. An advocate can negotiate and filter the market so you do not overpay for something that stretches your capacity.
Body corporate costs are a good example of what a headline price hides. I sold the first apartment in a Beenleigh complex in January 2021 for a developer who was openly sceptical that an agency of our size could move the stock. Five years on we have sold 12 apartments there. What made the difference was knowing everything about the complex, including the body corporate, and walking buyers through it honestly. When a buyer understands the ongoing costs before they sign, the number they set at the start is the number they stick to.
That is the link between finance and sales at George & Sons. Our finance team confirms what you can borrow across multiple lenders. Our sales team and buyers advocates then work to that figure, so you shop at the right price point, not the highest one a bank will allow.
Next step: book a free borrowing capacity assessment with the George & Sons finance team. Once your budget is confirmed, speak with our buyers advocates or browse current listings within your range.
Why the Maximum Number Is the Wrong Target
My view, after years of working with buyers on both sides of the table, is that the maximum borrowing capacity figure is the least useful number in the process. It tells you where a lender's policy ends, not where your financial life works best.
Buyers tend to treat the bank's number as permission. If a lender says $X, then $X becomes the target, and the search starts at the top of the range. The result is a purchase that technically passes the serviceability test and feels tight from the first month. A bank's model cannot see your plans for a baby, a career change or a renovation.
The more valuable thing a capacity assessment does is expose the spread. When you see how three lenders treat the same income and debts, you learn which of your financial habits are costing you the most. For many people it is not the salary. It is the card limits they forgot about, the BNPL account, or the way their bonus is documented. Those are fixable, and fixing them can lift the number without any change to how much you earn.
So my advice runs against the instinct. Use capacity modelling to find your constraints and your best lender fit. Then deliberately choose a budget under the maximum. The buyers who do this are the ones who can still act quickly when the right property appears, because they have room to move and no regrets about stretching.
The Beenleigh sales are a small illustration. The apartments were fresh, spacious and well priced, yet they still sold one at a time on trust, accurate information and genuine interest in what each buyer needed. A budget set with the same honesty gives you the same advantage.
References
- APRA, Australian Prudential Regulation Authority (residential mortgage lending settings and serviceability buffer announcements)
- ASIC MoneySmart, Home loan borrowing calculator
- ASIC, Responsible lending obligations for credit providers
- Melbourne Institute, Household Expenditure Measure (HEM) research
- Australian Taxation Office, Residential rental properties
Get tailored guidance
Send us your question and we will reply within one business day.
Send us the article topic, suburb, or property goal you want help with and we will reply within one business day.
Send my questionFAQ
How much can I borrow on my salary?
There is no fixed multiple. Your borrowing capacity depends on your income type, living expenses, existing debts, deposit and the lender's policy. As an outer boundary, a DTI of six means total debt of six times gross income, but many borrowers are limited well before that by serviceability. A lender-modelled assessment gives a real figure.
What is the serviceability buffer?
The serviceability buffer is the margin that lenders add to the loan's interest rate when testing whether you can afford repayments. APRA's minimum is currently 3 percentage points. If a loan carries a rate of 6 per cent, the lender checks that you could manage repayments at 9 per cent. Some lenders apply more than the minimum.
Does an unused credit card limit affect my borrowing capacity?
Yes. Lenders assess the card's limit, not its balance, because they assume you could draw on the full amount. Many treat a percentage of the limit as a monthly commitment. Reducing or closing unused cards before applying is one of the fastest ways to lift your capacity.
How accurate is a borrowing capacity calculator?
A borrowing capacity calculator gives a useful rough estimate, but it is not a lender decision. Calculators use generic assumptions about expenses, buffers and income, and they cannot see your credit file or documents. Treat the result as a starting point, then get a lender-specific assessment before you make offers.
Does HECS-HELP debt reduce borrowing capacity?
It can. HELP debt generates compulsory repayments through the tax system when your income passes the repayment threshold, which reduces your take-home income. Lenders treat it in different ways, so the effect varies. It is worth disclosing in full and comparing how different lenders handle it.
Margy George
Property and finance guidance from the George & Sons team.
Keep reading
pre-approval process
The Home Loan Pre-Approval Process in Australia: Step-by-Step Timeline, Documents and What Happens Next (2026)
18 min read
refinancing
Refinancing Your Home Loan in Australia: When to Switch, What It Costs and How to Do It in 2026
19 min read
home loans
Home Loans in Australia: A Buyer's Guide to Finance, Pre-Approval and Borrowing Power in 2026
15 min read
Ipswich 4300
Selling or renting out in 4300?
We specialise in sales and property management across the 4300 postcode. Pick your suburb for local rents, Census figures and how we work there.
Selling
Ready for clarity?
Get a calm, practical plan for your next property move.
Buying, selling, finance, or renting - tell us what you are working on and we will come back with the most useful next step.
Tell us what you need help with.
Send a quick enquiry and the team will come back with a clear next step.
Request a callback