home loans
Home Loans in Australia: A Buyer's Guide to Finance, Pre-Approval and Borrowing Power in 2026
A home loan is money you borrow from a bank or lender, secured against a property, and repaid with interest over a set term, typically 25 to 30 years. How much you can borrow depends on your income, debts, living expenses and the property's value. Getting finance sorted before you inspect properties gives you a real budget and a stronger negotiating position.
Most Australian buyers do this backwards. They fall in love with a house, then ring a bank to see if they can afford it. By the time finance enters the picture, they've already anchored emotionally to a property they may not be able to secure, or worse, they've made an offer they can't back up with a loan.
At George & Sons we sit across both sides of this equation. We sell property, we act as buyers advocates, we manage rentals, and we arrange finance. That vantage point matters here, because we regularly watch buyers lose ground, and sometimes lose the property outright, simply because they treated finance as paperwork instead of strategy. This guide walks through how home loans actually work in Australia in 2026, what genuinely moves your borrowing power, and why pre-approval belongs at the start of your search, not the end.
Key Takeaways
- Sorting finance before you start inspecting gives you a real budget and stronger negotiating position, particularly at auction.
- Borrowing power depends on income, existing debts, credit card limits, HECS/HELP debt and living expenses, not just your salary.
- Home loan pre-approval is conditional, not a guarantee, and typically lasts three to six months depending on the lender.
- Fixed, variable and split loans suit different risk appetites, and an offset account can meaningfully cut the interest you pay over the loan term.
- Investment loans are often priced differently to owner-occupier loans, which matters if you're weighing up rent-vesting.
- Loyalty rarely pays with a mortgage. Reviewing your loan every few years can save real money over its life.
Home Loan Structures at a Glance
| Structure | Rate Certainty | Flexibility (extra repayments/offset/redraw) | Best Suited To |
|---|---|---|---|
| Fixed rate | High, locked for the fixed period | Usually limited, extra repayments often capped | Buyers who want repayment certainty for budgeting |
| Variable rate | Low, moves with the lender and the cash rate | High, full access to offset and redraw | Buyers who want flexibility and can absorb rate movement |
| Split loan (part fixed, part variable) | Partial | Moderate, flexibility applies to the variable portion | Buyers who want a middle ground between certainty and flexibility |
| Interest-only (common on investment loans) | Depends on underlying rate type | Lower equity growth during the interest-only period | Investors managing cash flow or pursuing a rent-vesting strategy |
How a Home Loan Actually Works
A home loan lets you borrow a set amount, called the principal, which you repay with interest over an agreed term, usually 25 to 30 years. Lenders assess how much they'll lend based on the property's value, your deposit, and your capacity to service the debt.
The loan-to-value ratio (LVR) is the loan amount expressed as a percentage of the property's value. Put down a 10% deposit and your LVR is 90%. Most lenders require Lenders Mortgage Insurance (LMI) once your deposit falls below 20%, meaning your LVR sits above 80%. LMI protects the lender, not you, if you default, and the premium is usually added to your loan. Above 90% LVR, premiums climb sharply, and some lenders cap how high they'll lend at all.
What lenders are really assessing goes well beyond your payslip. They look at income stability and type (PAYG versus self-employed income is treated differently), your existing debts, your spending patterns from recent bank statements, your credit history, and your deposit's genuine savings history. Under guidance from the Australian Prudential Regulation Authority (APRA, apra.gov.au), lenders must also assess your ability to repay at a serviceability buffer, typically three percentage points above the actual loan rate, to make sure you could still manage repayments if rates rose. This buffer is a major reason two people on the same income can be offered very different borrowing amounts.
The Reserve Bank of Australia sets the cash rate at scheduled board meetings throughout the year, and lenders adjust variable home loan rates in response. After a sharp run of rate rises through 2022 and 2023 to bring inflation down, the RBA moved into an easing cycle from 2025 onward. The cash rate changes between meetings, so check the current figure directly at rba.gov.au rather than relying on a number you've seen elsewhere, particularly when you're calculating likely repayments.
Fixed vs Variable vs Split: Choosing the Right Loan Structure
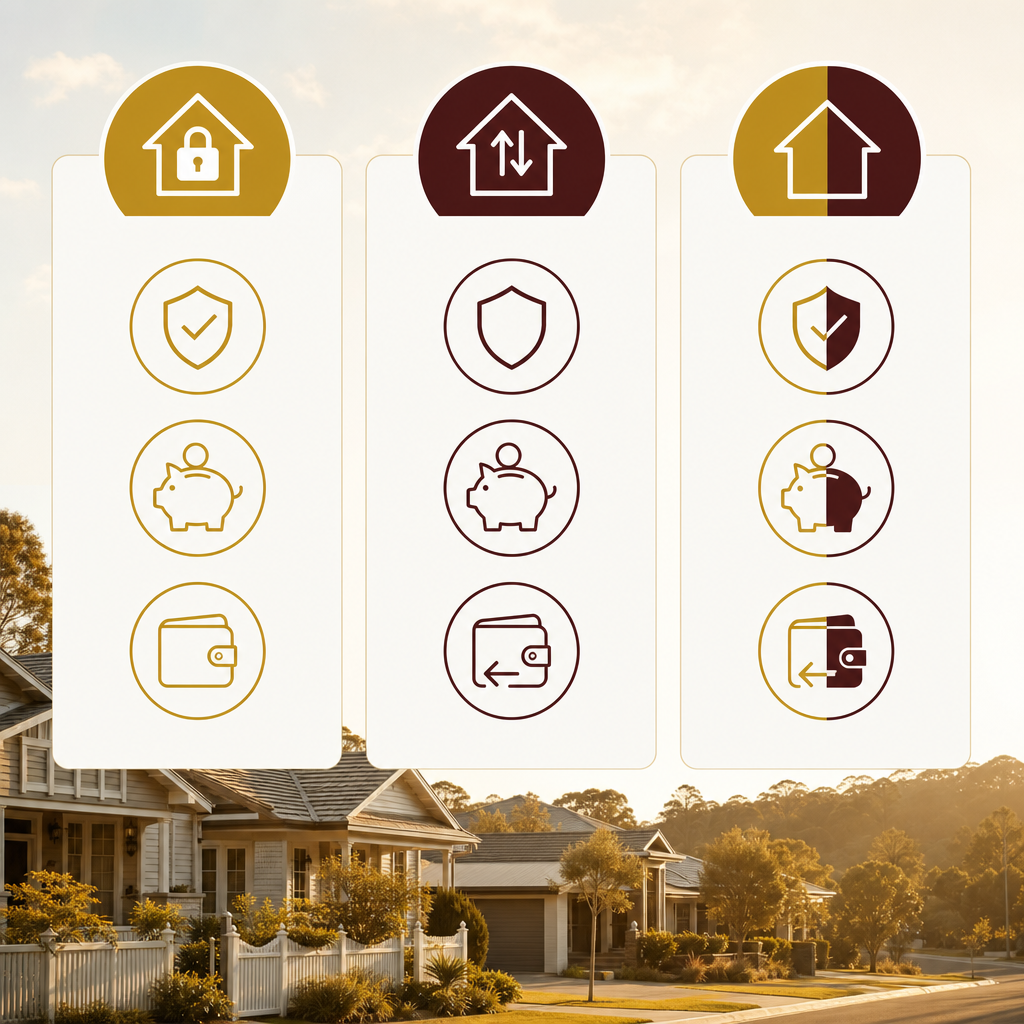
A fixed rate locks in certainty for a set period, a variable rate moves with the market and gives you flexibility, and a split loan lets you hold both at once. The right choice depends on how much budgeting certainty you need against how much flexibility you want to pay the loan down faster.
A fixed rate suits buyers who want to know exactly what their repayment will be for the next one to five years. The trade-off is limited flexibility. Most fixed loans cap extra repayments and charge break costs if you exit early, refinance, or sell during the fixed period.
A variable rate moves up and down with the lender's pricing and broader rate movements. You lose repayment certainty, but you gain full access to features like unlimited extra repayments, redraw, and an offset account. An offset account is a transaction account linked to your loan where the balance reduces the interest charged, without actually going towards your principal. Keep $20,000 sitting in an offset against a $600,000 loan and you're only charged interest on $580,000, while the money stays accessible. Redraw works differently: it lets you pull back extra repayments you've already made, but it's attached to the loan itself rather than sitting in a separate account, and some lenders restrict redraw access or charge a fee per withdrawal.
A split loan divides your borrowing into a fixed portion and a variable portion. It's a genuine middle ground: you get some rate certainty on part of the loan while retaining offset and extra repayment flexibility on the rest. We see split structures used most often by buyers who are risk-averse but still want to attack the loan aggressively where they can.
Borrowing Power: What Lenders Really Look At in 2026
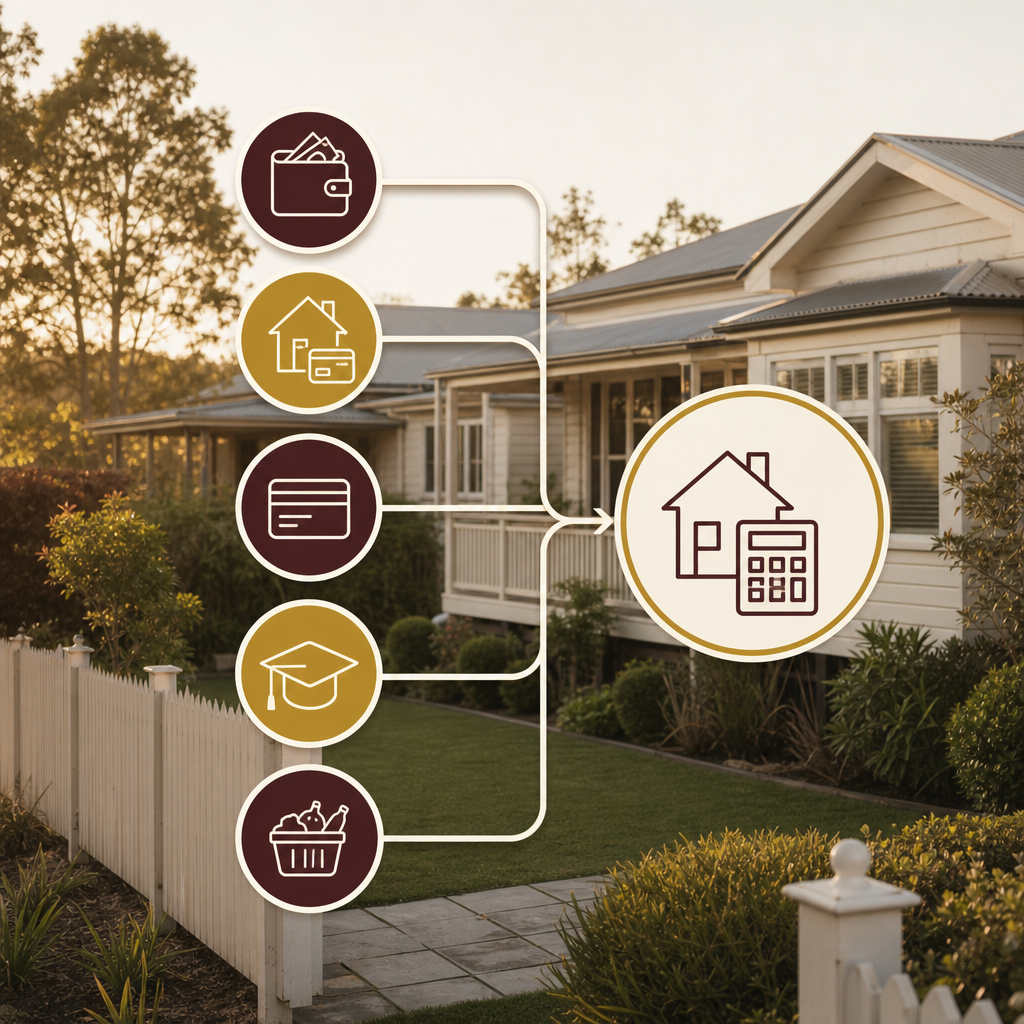
Borrowing power is the maximum amount a lender will offer you, and it's driven by net income, existing debts, credit card limits, HECS/HELP debt and living expenses, assessed against APRA's serviceability buffer. Two applicants earning identical salaries can be offered very different amounts once these factors are applied.
Income matters, but not all income is treated equally. Base salary is usually accepted in full, while overtime, bonuses and casual income are often discounted or excluded unless you can show a consistent history. Existing debts, including personal loans, car loans and buy-now-pay-later arrangements, are counted as ongoing commitments that reduce what's left for a mortgage repayment. Credit cards are assessed at their full limit, not your outstanding balance, so a $20,000 limit you never use still counts against you as if you owed it.
A HECS/HELP debt reduces borrowing power because it's treated as a compulsory repayment that lowers your net income, even though it isn't a traditional loan. Living expenses are benchmarked against the Household Expenditure Measure, a standard lenders reference alongside your actual bank statement spending, and lenders will use whichever figure is higher.
There are practical levers you can pull before you apply. Close or reduce the limit on credit cards you don't use. Pay down or clear personal loans and buy-now-pay-later balances. Avoid taking on new debt, including a new car loan, in the months before applying. Save a genuine deposit over time rather than relying on a lump sum gift close to application, since lenders look for a savings pattern. If you're applying with a partner, both incomes and both sets of liabilities are assessed together, so it's worth reviewing each other's accounts, not just your own.
Pre-Approval: What It Actually Means (and What It Doesn't)
Home loan pre-approval is a lender's conditional indication of how much they'll lend you, based on the information and documents you've provided, before you've found a specific property. It typically stays valid for three to six months, depending on the lender, and it is not a guarantee of final, unconditional approval.
Once a full application is submitted, the lender still needs to value the specific property, verify your final financial position, and confirm nothing has changed since pre-approval was issued. If you've taken on new debt, changed jobs, or your bank statements show different spending patterns, the lender can adjust or withdraw the offer.
Despite those limits, pre-approval changes how vendors and agents treat you. An agent fielding two similar offers will almost always favour the buyer who can demonstrate finance is sorted, because it removes the biggest source of settlement risk. At auction, pre-approval is close to essential: unconditional contracts mean there's no finance clause to fall back on if your loan falls through after the hammer falls.
Consider a buyer who inspects a property, makes an offer subject to finance, and has it accepted. They then start their loan application from scratch. Two weeks pass while the bank requests documents, the valuation comes in lower than expected, and the finance clause deadline lapses. The vendor, who had another offer waiting, moves on. The buyer didn't lose the property because they were outbid. They lost it because they hadn't done the finance groundwork before making the offer. This scenario plays out regularly across competitive Australian markets, and it's entirely avoidable with pre-approval in hand before you start inspecting.
Owner-Occupier vs Investment Property Loans
Investment property loans are often priced higher than owner-occupier loans, carry different serviceability tests, and more frequently use interest-only repayment periods. Lenders view investment lending as higher risk, partly because repayment can depend on rental income and partly due to regulatory settings from APRA around investor lending growth.
The rate differential between owner-occupier and investor loans has narrowed and widened over different cycles as APRA has tightened or eased investor lending settings, so it's worth comparing current investor rates specifically rather than assuming your existing owner-occupier rate will carry across. Interest-only periods, commonly available for one to five years on investment loans, reduce your repayment during that window but mean you're not building equity through principal reduction, only through capital growth if the market moves in your favour.
This is directly relevant if you're considering rent-vesting, where you buy an investment property in a market you can afford while continuing to rent where you actually want to live. The loan structure you choose, interest-only versus principal and interest, fixed versus variable, has a real effect on cash flow and on how the strategy performs over time. We've written a separate rent-vesting guide that goes into this strategy in more depth, and it's worth reading alongside this article if you're weighing up buying to live in versus buying to invest.
Refinancing and Loan Reviews: The Cost of Loyalty
Refinancing means replacing your current home loan with a new one, usually to get a better rate, access equity, or switch features like an offset account. Signs your loan has gone stale include a rate noticeably above what new customers are offered, a lack of an offset account, or simply not having reviewed the loan in two to three years.
Lenders routinely price new customers more sharply than existing ones, a pattern sometimes called the "loyalty tax". A loan that was competitive when you signed it can quietly fall behind the market within a couple of years, particularly during periods when the cash rate is moving. Refinancing costs, including discharge fees, application fees and sometimes Lenders Mortgage Insurance again if your LVR has changed, need to be weighed against the savings, but for many borrowers the maths still favours a review.
This is also where the mortgage broker versus bank question comes in. According to the Mortgage & Finance Association of Australia (MFAA, mfaa.com.au), brokers have settled the majority of new residential home loans in Australia for several years running, largely because they compare multiple lenders rather than a single institution's own products. Going direct to your existing bank means comparing against one lender's offer; a broker (or an in-house finance team like ours) compares your current loan against the wider market, including lenders you may not have considered.
Why We Insist on Talking Finance Before Floor Plans
Most real estate businesses only see one side of a transaction: the sale. We see the finance conversation, the buyers advocacy process, and the property management outcome on the same deals, which is unusual, and it's why we push finance to the front of the process rather than the back.
The clearest lesson we've learned about trust building on the sales side applies just as much to finance. Several years ago we were referred in to appraise a freshly built apartment complex in Beenleigh. The developer had been through other agents and was openly sceptical when we first met, telling us he wasn't convinced we could actually move the units but was willing to let us try. We made a point of knowing the complex, the body corporate structure and the numbers inside out, and treated every buyer's situation as genuinely individual rather than running a generic sales script. We sold the first apartment, then the second, and confidence grew from there. Five years on, we've sold twelve apartments in that complex and the developer has become a genuine friend of the business.
That pattern, earning trust through depth of knowledge and attention to the buyer's actual situation rather than a quick pitch, is exactly what we apply to finance conversations. A buyer who understands their real borrowing power, has pre-approval sorted, and knows the difference between an owner-occupier and investment structure walks into an inspection, or an auction, in a completely different position to one who's still guessing. We'd rather have that conversation in week one than watch a buyer lose a property in week four because the finance side was an afterthought.
If you want the fuller picture on current buying conditions, our 35 Australian Real Estate Market Statistics article and our general buying guide are worth reading alongside this one, and our buyers advocacy team and finance service hub can walk you through your specific numbers rather than general ranges.
References
- Reserve Bank of Australia, Cash Rate Target: https://www.rba.gov.au/statistics/cash-rate/
- Australian Bureau of Statistics, Lending Indicators: https://www.abs.gov.au/statistics/economy/finance/lending-indicators
- Australian Prudential Regulation Authority (APRA), guidance on mortgage serviceability standards: https://www.apra.gov.au/
- Mortgage & Finance Association of Australia (MFAA), broker market share reporting: https://www.mfaa.com.au/
- ASIC MoneySmart, home loan and refinancing guidance: https://moneysmart.gov.au/home-loans
Get tailored guidance
Send us your question and we will reply within one business day.
Send us the article topic, suburb, or property goal you want help with and we will reply within one business day.
Send my questionFAQ
How much deposit do I need for a home loan in Australia?
Most lenders prefer a 20% deposit to avoid Lenders Mortgage Insurance, but many will lend with as little as 5-10% deposit, subject to LMI and a higher LVR. A larger deposit generally improves your rate and reduces total interest paid.
How long does home loan pre-approval last?
Pre-approval typically lasts three to six months depending on the lender, after which you'll usually need to renew it if your search takes longer. It's conditional, not a final guarantee of the loan.
Is a mortgage broker better than going direct to a bank?
A broker compares products across multiple lenders and is paid by the lender rather than the borrower in most cases, while going direct means comparing only that bank's own range. According to MFAA data, brokers now settle the majority of new residential loans in Australia, largely for this reason.
Does my HECS/HELP debt affect my borrowing power?
Yes. A HECS/HELP debt is treated as a compulsory repayment that reduces your net income in a lender's serviceability assessment, which can lower the amount you're able to borrow even though it isn't a conventional loan.
Are investment property loan rates higher than owner-occupier rates?
Often, yes. Lenders generally price investment lending differently to owner-occupier lending and apply different serviceability tests, partly reflecting APRA's regulatory settings around investor lending. It's worth comparing investor-specific rates rather than assuming your current rate applies.
When should I consider refinancing my home loan?
Consider refinancing if you haven't reviewed your loan in two to three years, your rate sits noticeably above current offers, or your loan lacks features like an offset account. Weigh any discharge or application fees against the likely savings before switching.
Margy George
Property and finance guidance from the George & Sons team.
Keep reading
borrowing capacity
Borrowing Capacity in Australia: How Lenders Calculate It and 7 Ways to Increase It in 2026
21 min read
refinancing
Refinancing Your Home Loan in Australia: When to Switch, What It Costs and How to Do It in 2026
19 min read
first home buyer finance
First Home Buyer Finance in Australia: Grants, Schemes, Deposits and How to Fund Your First Purchase in 2026
16 min read
Ipswich 4300
Selling or renting out in 4300?
We specialise in sales and property management across the 4300 postcode. Pick your suburb for local rents, Census figures and how we work there.
Selling
Ready for clarity?
Get a calm, practical plan for your next property move.
Buying, selling, finance, or renting - tell us what you are working on and we will come back with the most useful next step.
Tell us what you need help with.
Send a quick enquiry and the team will come back with a clear next step.
Request a callback