Investment property loans
Investment Property Loans in Australia: How to Structure, Qualify and Borrow for Your Next Investment in 2026
Investment property loans in Australia are assessed more strictly and usually priced higher than owner-occupier loans. Lenders test your repayments at a buffer of at least 3 percentage points above the loan rate, count only part of your expected rent, and typically want a 20% deposit or equity to avoid Lenders Mortgage Insurance.
Most investors do not fail because they picked the wrong suburb. They stall because the loan was set up badly: the wrong repayment type, the wrong security structure, or a rental income assumption the lender never accepted. A poor structure limits what you can buy next, long before the property itself becomes the problem.
This guide covers only what is different for investors. We assume you already understand how a standard home loan works. From here, we look at how lenders assess investment borrowing, how equity and deposits work, when interest only makes sense, and how finance, purchasing and property management fit together. I'm Alex Frew, founder of 3P Digital, writing for George & Sons, where one team handles finance, buyers advocacy, sales and property management.
Key Takeaways
- Investment loans are tested harder than owner-occupier loans. Expect a rate premium, the APRA serviceability buffer, and shaded rental income.
- A 20% deposit (or an LVR of 80% or less) generally avoids Lenders Mortgage Insurance. Equity in your home can replace a cash deposit, but you still need cash for purchase costs.
- Interest only improves short-term cash flow. It does not reduce your debt, and your repayments rise when the interest-only period ends.
- Lenders commonly count around 70-80% of rent when assessing serviceability. A realistic rental appraisal protects you from overestimating capacity.
- Structure matters as much as rate: separate securities, split loans and a considered offset account keep your options open.
- The best outcomes come when the loan, the purchase and the rental strategy are planned together.
Summary Table: Investment Loans at a Glance
| Topic | What lenders typically do | What it means for you |
|---|---|---|
| Interest rate | Price investment loans above owner-occupier loans | Compare rates on the day, and factor the premium into your cash flow |
| Serviceability | Apply the APRA buffer above the actual loan rate | Your borrowing capacity is lower than your repayments suggest |
| Deposit and LVR | Require a lower LVR to avoid LMI | Plan for the deposit plus stamp duty and costs |
| Equity | Allow borrowing against usable equity in your home | Can replace a cash deposit, but increases total debt |
| Interest only vs P&I | Assess IO loans on the P&I repayment over the remaining term | IO helps cash flow now but reduces assessed capacity |
| Rental income | Count only a portion of rent | A realistic appraisal prevents surprises |
| Structure | Prefer cross-collateralised security | Standalone securities keep flexibility |
How Do Investment Loans Differ From Owner-Occupier Loans?
 Investment loans cost more and are tested harder than owner-occupier loans. Lenders typically charge a higher interest rate, apply the APRA serviceability buffer, shade your rental income, and count your existing debts in full. Two borrowers on identical incomes can end up with very different borrowing capacity depending on the purpose of the loan.
Interest rates and the investor premium
When people search for investment loan interest rates in Australia, they usually find that investor rates sit above owner-occupier rates, and interest only rates sit higher again. Part of this is legacy: APRA previously leaned on lenders to slow investor and interest-only lending, and pricing differences stuck. Part of it is risk. Lenders view investors as more likely to default in a downturn than someone living in the property.
The size of the gap changes by lender and over time, so we won't quote a single figure here. The RBA's cash rate target sets the baseline for variable rates, and you should check the current rate on the RBA website before you model any scenario. What matters for your plan is that the rate you see advertised for owner-occupiers is not the rate you will pay.
The serviceability buffer
APRA requires lenders to assess borrowers at a rate at least 3 percentage points above the loan's actual interest rate. In practice, a loan priced at a given rate is tested as though it were three points higher. Add the investor premium and a higher assessment floor at some lenders, and the test gets tougher still.
APRA has also moved to limit the share of new lending that goes to borrowers with very high debt-to-income ratios. This matters most for leveraged investors with several loans. Confirm the current settings with your broker, because lender policy responds quickly to regulator signals.
Lender policy is not uniform
This is where investors gain or lose the most. Lenders differ on how much rent they count, whether they give credit for negative gearing tax benefits, how they treat existing investment debts, and which property types they will lend against. Some restrict small apartments or high-density complexes. A loan declined by one lender may be approved by another on identical numbers.
The ABS Lending Indicators release reports investor housing loan commitments separately from owner-occupier commitments each month. Investor lending is cyclical. It tends to strengthen when rate expectations ease and weaken when borrowing costs rise. That is useful context, but your lending decision should be driven by your own numbers, not by headlines.
What Deposit Do You Need for an Investment Property?
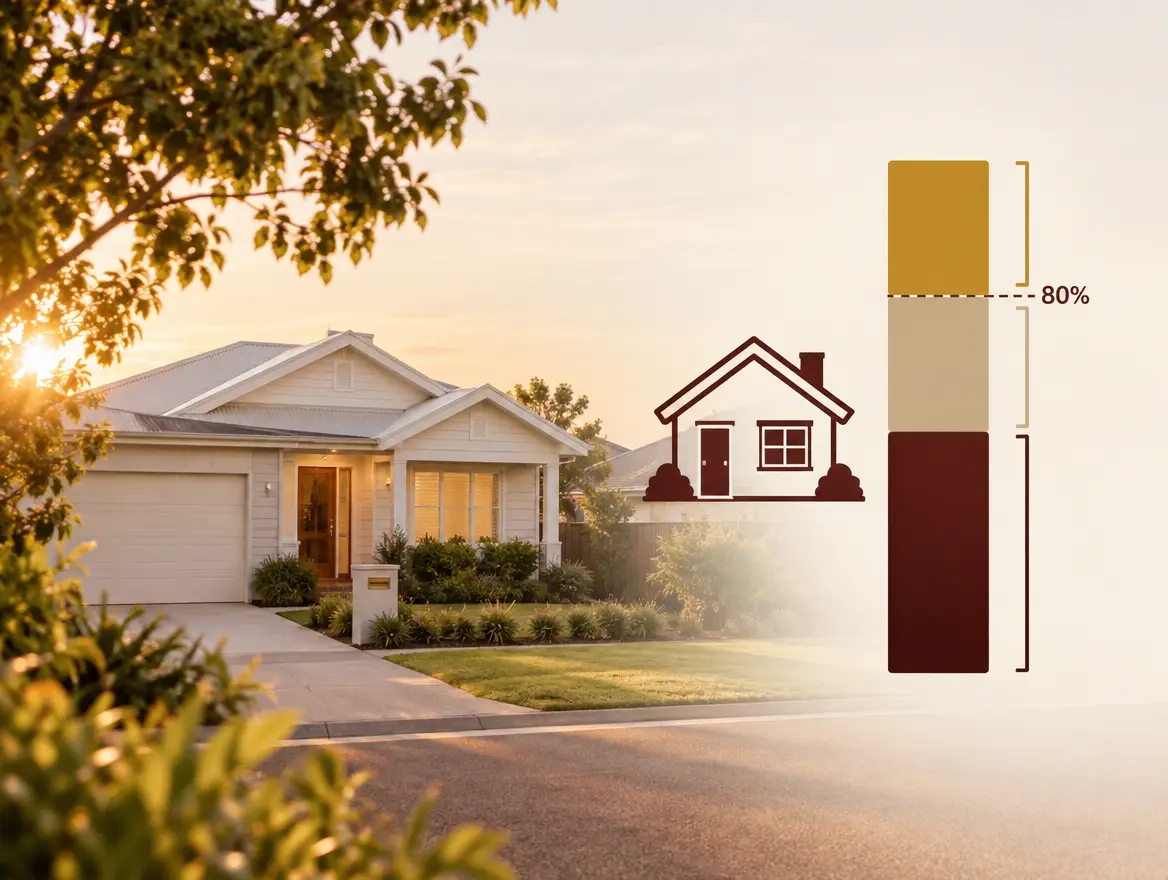 Most lenders want at least a 20% deposit on an investment property to avoid Lenders Mortgage Insurance (LMI). That means a loan-to-value ratio (LVR) of 80% or less. You can fund the deposit from savings or from usable equity in your existing home, but you still need cash for stamp duty and purchase costs.
LVR and LMI for investors
Some lenders will go above 80% LVR on investment purchases, with LMI added. Others set lower limits for investors than for owner-occupiers, and some limit LVR further on units or small apartments. LMI protects the lender, not you, and it can usually be capitalised into the loan. That increases your debt and your interest bill.
Borrowing with LMI can still be a rational choice when it gets you into a well-located asset sooner. It should be a deliberate decision with the cost modelled, not a default.
Using equity to buy an investment property
Using equity to buy an investment property is the most common path for existing homeowners. Equity is the gap between your home's value and what you owe. Lenders typically let you borrow up to 80% of the value, less your existing debt.
Consider a hypothetical home valued at $900,000 with a $450,000 loan. At 80% of value ($720,000), usable equity would be around $270,000, subject to a lender's valuation and serviceability. That $270,000 could fund a deposit and costs on a purchase.
The structure matters here. The best practice is to draw the equity as a separate loan secured against your home, and secure the new investment loan against the new property alone. This is a standalone structure, and it avoids the trap we cover below under cross-collateralisation.
Two cautions. Equity is not free money: you are adding debt against your family home, and your repayments are still tested at the buffer rate. And a valuation can come in lower than expected, which shrinks the equity you thought you had.
Costs beyond the deposit
Budget for stamp duty (which varies by state and territory), legal and conveyancing fees, building and pest inspections, and lender fees. Landlord insurance and an initial buffer for vacancy are also sensible. Many investors underestimate this cash requirement and are forced to use more equity than planned.
Interest Only vs Principal and Interest: Which Suits an Investor?
Interest only loans have lower repayments for a set period, commonly one to five years, because you pay no principal. Principal and interest (P&I) loans cost more each month but reduce your debt. Interest only suits investors prioritising cash flow and tax-deductible debt, while P&I suits those wanting lower long-term interest cost and less risk.
A worked example
This is an illustration only. The 6.50% p.a. rate is hypothetical, not a quote, and the figures are rounded. Consider a $600,000 investment loan over 30 years.
- Interest only (first 5 years): about $3,250 per month, or $39,000 a year. The loan balance stays at $600,000.
- Principal and interest (30 years): about $3,792 per month. After 5 years, the balance would be roughly $561,700, so about $38,300 of principal has been repaid.
- Monthly saving on interest only: roughly $542 during the interest-only period.
- When the interest-only period ends: the remaining 25-year P&I repayment on $600,000 would be about $4,051 per month. That is about $259 more than the original 30-year P&I repayment, because you now repay the same debt over a shorter time.
The lesson is that interest only defers cost rather than removing it. You save about $542 a month for five years, then pay more for the next 25 years, and you owe the same amount at the end of the interest-only period.
Tax considerations
Interest on a loan used to buy a rental property is generally tax-deductible, while principal repayments are not. This is why many investors favour interest only: it maximises the deductible portion and keeps cash free for other uses. The ATO's guidance on rental properties sets out what is and is not deductible, and the purpose of the borrowing is what counts. Speak to a registered tax agent about your situation.
Avoid choosing interest only purely for the deduction. A deduction reduces your tax, but you still spend a dollar of interest to get back part of it.
When each suits
Interest only tends to suit investors who want to preserve cash flow, who hold surplus cash in an offset account, who are paying down non-deductible home debt first, or who expect to sell before the period ends.
P&I tends to suit investors who want certainty, who plan to hold long term, or who are close to the edge on cash flow in a rate rise. Lower debt is also a buffer if values soften.
One point catches many borrowers. Lenders usually assess interest only loans on the P&I repayment over the remaining term. A five-year interest-only period is therefore assessed over 25 years, which raises the assessed repayment and can reduce your borrowing capacity. Interest only improves your actual cash flow but can hurt your capacity to borrow.
How Do Lenders Treat Rental Income?
Lenders do not count all of your rent. They typically shade it to around 70-80% of gross rent in their serviceability calculations, to allow for vacancy, management fees, repairs and rates. This is a general range, and each lender sets its own policy. A realistic rental appraisal keeps your assumptions in line with what the lender will accept.
Rental income and borrowing capacity
Rental income and borrowing capacity are linked, but the link is weaker than most investors assume. Consider a hypothetical property rented at $600 a week. That is $31,200 a year. At 80% shading, the lender counts about $24,960. At 70%, it counts about $21,840. The difference is over $3,000 a year of assessed income, which flows through to how much you can borrow.
The lender then compares that shaded income and your other income against your assessed commitments at the buffered rate. Existing investment loans are counted too. Each additional property therefore consumes capacity faster than the last.
Why an accurate rental appraisal matters
Lenders may rely on a valuer's rental estimate, a signed lease, or an agent's appraisal. If you assume a high rent and the lender uses a lower number, your capacity drops after you have already paid for a contract. Worse, if you buy on an inflated rent assumption, your real cash flow will not match your plan.
Get a rental appraisal before you commit, not after settlement. A local property manager sees current tenant demand, vacancy rates and comparable leases, which is data a lender's model does not have. For new builds and off-the-plan purchases, be especially cautious. Appraisals tied to a developer's marketing can be optimistic.
Rental income before you own the property
If you are buying, lenders usually require evidence of the expected rent. If you already own and are refinancing, they will use your current lease or ledger. Either way, stable, well-documented rent makes the assessment smoother.
Negative Gearing and Your Investment Loan
Negative gearing means your deductible property costs, including loan interest, exceed your rental income, creating a loss you can offset against other taxable income. It reduces your tax but still costs you cash. A loan structure that chases deductions without a plan for growth and cash flow can leave you worse off.
People often treat a negatively geared property as a tax strategy. It is better understood as a holding cost you accept in exchange for expected long-term capital growth. If growth does not arrive, the tax deduction does not make up the loss.
Three practical points for your loan:
- Cash flow comes first. You pay the shortfall now and receive the tax benefit later, typically at tax time or through a PAYG variation. Make sure you can carry the shortfall comfortably.
- Lenders vary on tax benefits. Some give partial credit for negative gearing in serviceability, others give none. Ask your broker how each lender treats it.
- Record-keeping is essential. Interest is deductible based on what the borrowed funds were used for. Mixing investment and personal borrowings in one loan creates messy records and can reduce your deductions.
This is general information. A registered tax agent or accountant can tell you how negative gearing applies to your circumstances.
How Should You Structure an Investment Loan?
A good investment loan structure keeps each property secured separately, separates deductible and non-deductible debt, and uses features such as split loans and offset accounts where they fit your plan. Structure is set at the start and expensive to fix later, so decide it before you sign.
Split loans
A split loan divides your borrowing into portions with different terms. You might fix part of the loan for repayment certainty and leave part variable so you can make extra repayments or use an offset. You might also hold part on interest only and part on P&I. Splitting gives you flexibility, but each split can add fees, so weigh the benefit.
Offset accounts
An offset account reduces the interest charged by netting the balance against your loan. It keeps cash accessible and, unlike extra repayments, does not change the loan's deductible balance. Many investors keep spare cash in an offset on the investment loan while repaying non-deductible home debt first. Whether that suits you is a tax question, so confirm it with your accountant.
Avoiding cross-collateralisation
Cross-collateralisation means one lender holds multiple properties as security for multiple loans. It is convenient for the lender and risky for you. It can make it harder to sell one property, restrict your ability to refinance, and let the lender revalue everything at once.
Use standalone securities where possible. One loan secured against one property keeps your options open. This is particularly important when you plan to use equity from your home to buy an investment property, because it prevents the new debt from tying up the family home.
Common Mistakes Investors Make When Choosing a Loan
The most common investor loan mistakes are chasing the lowest advertised rate, overestimating rent, ignoring the interest-only cliff, and cross-collateralising securities. Each one limits flexibility or borrowing capacity later, often just when you want to buy again.
- Choosing on rate alone. A low rate with a rigid structure can cost more than a slightly higher rate with the features you need.
- Using an optimistic rent figure. Lenders will shade it, and the real market will test it.
- Ignoring the end of the interest-only period. Plan for the higher repayment from day one.
- Cross-collateralising everything. It limits your ability to sell, refinance or switch lenders.
- Forgetting running costs. Rates, insurance, repairs, body corporate levies and management fees all reduce net income. See our guide on property management fees in Australia for what to budget.
- Stretching to maximum borrowing. Borrowing capacity is a ceiling, not a target. A rate rise or a vacancy can strain an investor at the limit.
- Leaving the loan unreviewed. Your lender's investor rate will drift. Review the loan regularly and ask for a better rate or refinance when it makes sense.
How Finance, Buyers Advocacy and Property Management Work Together
Loan structure, property selection and rental performance affect each other. Finance sets your budget and structure, a buyers advocate finds a property that meets lender policy and rental targets, and a property manager confirms the rent and keeps the asset earning. Planning them together avoids expensive mismatches.
Here is how that looks in practice at George & Sons, where finance, buyers advocacy, sales and property management sit under one roof.
- Finance defines the boundaries. Before you search, we confirm borrowing capacity, the equity you can use, the structure, and the lender policies that apply.
- Buyers advocacy works within them. A property that suits your loan is one the lender will value and lend against, in a location with real tenant demand.
- Rental appraisal tests the numbers. Before you commit, a local rental appraisal confirms the rent your serviceability calculation relies on.
- Property management protects the result. Good tenant selection, fast leasing and regular reviews keep vacancy and arrears low, which protects your cash flow and your next loan application.
When these services are separate, the broker doesn't know the rent, the buyers agent doesn't know the lender's policy, and the manager inherits a property that was bought on assumptions nobody tested. Joining them up is simply common sense.
Why the Loan Should Be Built Around Holding the Property, Not Just Buying It
I hold a view that runs against how most lenders and many brokers talk about investment lending. Borrowing capacity is the wrong question. The better question is whether you can hold the property through a vacancy, a rate rise and a major repair, without being forced to sell.
A lender's serviceability test is a regulator-driven pass or fail. It tells you what a bank will lend. It doesn't tell you what you can comfortably carry. Many of the investors who get into trouble passed the test.
I saw the practical side of this from the sales side. In January 2021, a developer who owned a Beenleigh apartment complex was referred to us for an appraisal. He was sceptical and told me he wasn't sure I could do much, but he would give it a go. I sold the first apartment that month. Five years on, we have sold 12 apartments in the complex, and he is now a good friend.
What made the difference wasn't clever marketing. The apartments were new, clean and spacious, and they were not hard to sell on their own merits. I made sure I knew everything about the complex and its body corporate, and I walked buyers through it. I paid genuine attention to what each purchaser needed.
That last point matters for investors. If you buy into a strata complex, the body corporate is part of your investment. Levies, sinking fund position and building details affect your net yield and, in some cases, how a lender views the security. Buyers who understand the body corporate before they sign make better decisions and have fewer surprises.
So my advice is to build the loan around the hold. Keep a cash buffer in your offset. Choose a structure that lets you sell one property without disturbing the others. Test your rent with a local appraisal. And look at the running costs of the specific property, not only the loan.
This approach often means borrowing less than the maximum. In my experience, the investors who build a portfolio over many years are the ones who never had to sell at a bad time.
Next Steps
If you would like to know how much you could borrow for an investment property, book an obligation-free chat with the George & Sons finance team. We will assess your borrowing capacity, your usable equity and the structure that fits your plan. If you already have a property in mind, you can also request a rental appraisal or speak with one of our buyers advocates. You can find our contact details and office locations on the George & Sons website.
General advice disclaimer: this article is general information only and is not personal financial, credit or tax advice. It does not consider your objectives, financial situation or needs. Interest rates, lender policies and regulations change, so verify current figures with the sources below and seek advice from a licensed finance professional and a registered tax agent before making decisions.
References
- Reserve Bank of Australia, Cash Rate Target: https://www.rba.gov.au/statistics/cash-rate/
- Australian Prudential Regulation Authority (APRA), Prudential Practice Guide APG 223 Residential Mortgage Lending and mortgage serviceability buffer announcements: https://www.apra.gov.au
- Australian Bureau of Statistics, Lending Indicators: https://www.abs.gov.au/statistics/economy/finance/lending-indicators/latest-release
- Australian Taxation Office, Residential rental properties: https://www.ato.gov.au/individuals-and-families/investments-and-assets/residential-rental-properties
- ASIC MoneySmart, Home loans: https://moneysmart.gov.au/home-loans
Get tailored guidance
Send us your question and we will reply within one business day.
Send us the article topic, suburb, or property goal you want help with and we will reply within one business day.
Send my questionFAQ
What deposit do I need for an investment property in Australia?
Most lenders want a 20% deposit, which means an LVR of 80% or less, to avoid Lenders Mortgage Insurance. Some lenders accept less with LMI added. You also need cash for stamp duty, legal fees, inspections and lender costs, so your total cash requirement is more than the deposit alone.
Is interest only or principal and interest better for an investment loan?
Neither is better for everyone. Interest only lowers repayments for a set period and maximises deductible interest, but your debt does not fall and repayments rise when the period ends. P&I costs more now but reduces debt. The right choice depends on your cash flow, plans and tax position.
Can I use equity in my home to buy an investment property?
Yes. Lenders typically let you borrow up to 80% of your home's value, less your existing debt, subject to serviceability and a valuation. It is best to draw the equity as a separate loan and secure the new purchase against the new property, to avoid cross-collateralisation.
How much rental income do lenders count?
Lenders typically count around 70-80% of gross rent, as a general range. Each lender sets its own policy. The shading allows for vacancy, management fees, repairs and rates, so assessed income is lower than your actual rent.
Are investment loan interest rates higher than owner-occupier rates?
Generally, yes. Lenders price investment loans above owner-occupier loans, and interest only loans usually sit higher again. The gap varies by lender and changes over time, so compare current rates when you apply, and check the RBA cash rate for context.
Margy George
Property and finance guidance from the George & Sons team.
Keep reading
negative gearing Australia
Negative Gearing in Australia Explained: How Property Investors Reduce Tax in 2026
26 min read
buying investment property australia
Buying Your First Investment Property in Australia: A Complete Guide for 2026
25 min read
first home buyer finance
First Home Buyer Finance in Australia: Grants, Schemes, Deposits and How to Fund Your First Purchase in 2026
16 min read
Ipswich 4300
Selling or renting out in 4300?
We specialise in sales and property management across the 4300 postcode. Pick your suburb for local rents, Census figures and how we work there.
Selling
Ready for clarity?
Get a calm, practical plan for your next property move.
Buying, selling, finance, or renting - tell us what you are working on and we will come back with the most useful next step.
Tell us what you need help with.
Send a quick enquiry and the team will come back with a clear next step.
Request a callback